

Got PCS Orders? Should You Sell, Rent or Take a Cash Offer on Your Crestview Home?

By Tanya Rivera · REALTOR®, Military Relocation Specialist · The Property Group 850, Inc.
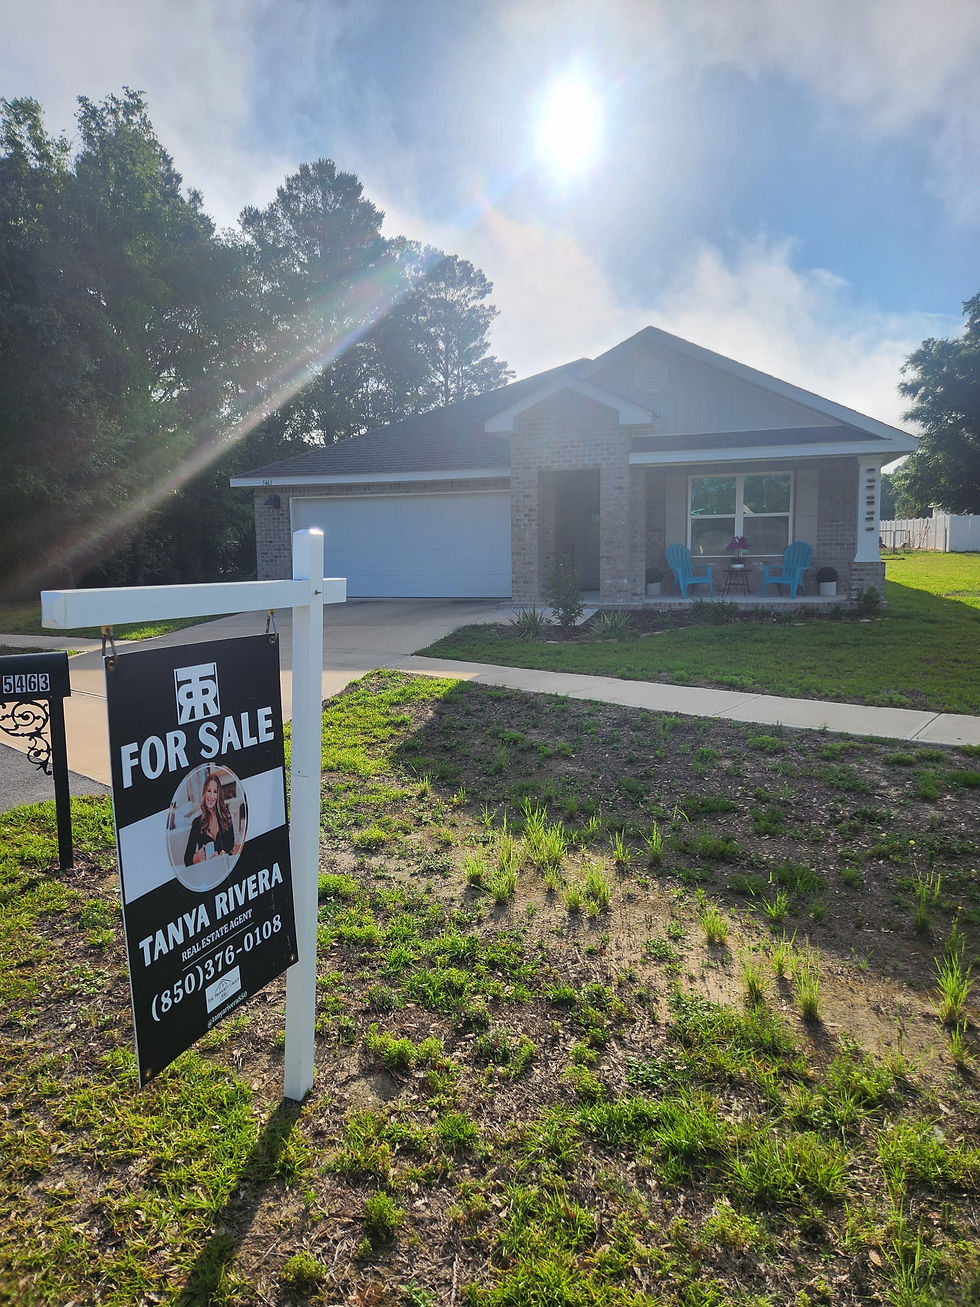
Short answer: If you don't want to be a long-distance landlord and you may want to use your VA loan again at your next duty station, selling before you leave Crestview is usually the cleanest move. Renting can make sense if your rent will cover the mortgage with room to spare and you have a plan for management. A cash offer trades price for speed, so only take one after you've seen what the open market would pay you.
When orders come down, most of the advice online is written for the family moving to the Emerald Coast. Almost nobody writes for the family that already owns a home in Crestview and now has 60 to 120 days to figure out what to do with it. That's who this post is for.
I'm a Crestview native and I've sold homes here since 2015, a lot of them for military families on their way out. Below are the three real options, what each one costs you, and the questions I ask every seller before we pick one.
Key takeaways
Selling and paying off your VA loan lets you restore that entitlement for your next purchase. Renting keeps it tied to this house.
Service members on qualified extended duty can suspend the IRS 5-year test for the capital gains exclusion for up to 10 years, which can change the rent-vs-sell math. Confirm with a tax advisor.
Renting a Florida home can affect your homestead exemption. Call the Okaloosa County Property Appraiser before you sign a lease.
Cash offers are fast, but they usually come in under market. Get an agent's pricing first so you know what you're giving up.
You don't have to be in Crestview to close. Florida allows remote online notarization.
Option 1: Sell before you leave Crestview
This is the option I see work best for most families, mostly because it's the one with the fewest loose ends.
Why families choose it
Your VA entitlement comes back. When the home sells and the VA loan is paid off, you can apply to have your full entitlement restored. That matters if you want to buy with $0 down at your next duty station.
One mortgage, not two. You don't carry a Crestview payment while you're also paying rent or a new mortgage somewhere else.
No landlord calls from 1,000 miles away. No AC failures at 2 a.m., no tenant turnover, no vacancy months.
You can sell while the house still shows like a home. Homes show best before the movers pack it up, and buyers in Crestview are often military families on their own PCS clock.
What it takes
Start early. I like to talk 60 to 90 days before your report date, even if you're not listing yet.
Decide what gets fixed before listing and what gets priced in. Not every repair pays for itself.
Line up your timing with your household goods pickup. We can list before the pack-out, after it, or with the house vacant, and each one changes how the home shows.
Where it can go wrong: pricing for what a neighbor got two years ago instead of what's selling now. I'll pull current sold comps from your subdivision, whether that's Redstone Commons, Lee Farm, Shoal River Landing or anywhere else in Crestview, so your price is set by today's market.
Option 2: Keep it and rent it out
Plenty of military families build real wealth by keeping a home at each duty station. It can work in Crestview because there's steady rental demand from Eglin, Duke Field and Hurlburt. But it only works when the numbers and the plan are both solid.
Run these numbers before you decide
Rent vs. your full payment. Compare realistic rent to principal, interest, taxes, insurance and HOA dues, not just principal and interest.
Property management. Budget for a manager unless you have someone local you trust. Self-managing from another state rarely goes well.
Vacancy and repairs. Plan for at least a month empty between tenants and a reserve for the big items: roof, AC, water heater.
Insurance. A rental needs a landlord policy, and Florida insurance costs have climbed. Get a quote before you commit.
Three things people don't think about
Your VA entitlement stays tied up. As long as that VA loan is open, part of your entitlement is in use. You may still have enough left for another VA loan, but in higher-priced areas it can mean a down payment. Ask your lender to run your remaining entitlement for your next duty station.
Your homestead exemption. Florida's homestead exemption is for your permanent residence, and renting the home can affect it, which can raise your property taxes. Rules for service members can differ, so call the Okaloosa County Property Appraiser's office before you sign a lease.
The capital gains clock. Normally you need to have lived in the home 2 of the last 5 years to exclude the gain when you sell. Members of the uniformed services on qualified official extended duty can suspend that 5-year period for up to 10 years. That gives you more room to rent first and sell later, but talk to a tax advisor about your dates.
My honest take: renting works best when the home already cash-flows with a manager, you have reserves, and you'd actually want to own a Crestview rental for the long haul. If the plan is "rent it until the market gets better," let's look at the numbers together first.
Option 3: Take a cash offer (and what it really costs)
If you've owned a home near a base, you've probably gotten the postcards and texts: "We'll buy your house as-is, close in 7 days." When you're staring at a report date, that can sound like relief.
When a cash offer can make sense
The home needs major repairs you can't manage from a distance.
Your report date is so close that a normal 30 to 45 day closing won't fit.
You simply value certainty over price, and you've decided that with eyes open.
What it costs you
Investors who buy for cash need room for their repairs, their holding costs and their profit, so their offers usually land below what the same house would bring on the open market. On a typical Crestview home, that gap can be large enough to cover a full move. The postcard rarely mentions that.
How to protect yourself
Get a market price from a local agent first, so you can see the real gap between cash and open market.
Read the contract for inspection periods and escape clauses. Some "cash offers" get renegotiated after the buyer's inspection.
Ask whether the buyer plans to assign the contract to someone else. That's a sign you're dealing with a middleman, not the end buyer.
Remember you can do both: list the home and still consider a cash buyer if one shows up with fair terms.
I'll gladly look over any cash offer you've received, no strings attached. Sometimes it's a fair deal for your situation. Often it isn't.
Already moved? Selling your Crestview home from out of state
A lot of the sellers I work with call me after they've already reported somewhere else. That's fine. Selling remotely is very doable when someone local is handling the details.
What I handle on the ground
A walkthrough of the empty house with photos and video, so you see what buyers will see
Getting quotes from local vendors for cleaning, lawn care, paint or repairs, and sending them to you before anything is approved
Professional photos and listing prep
Showings, buyer inspections and appraisal access
Regular updates by text or video, on your schedule and your time zone
Closing without flying back
Florida allows remote online notarization, and many title companies can also mail documents for you to sign with a local notary or at your installation's legal office. Your closing agent will tell you which method they use, so ask early. If your spouse is deployed or unavailable, talk to the closing agent about a power of attorney well before closing. Many title companies need to review and approve a POA in advance.
Keep the house protected while it's empty
Tell your insurance company the home is vacant, because some policies limit coverage after a set number of days. Keep the utilities on so the AC runs, since Florida humidity in a closed-up house can turn into a mold problem quickly.
A selling timeline that works backward from your report date
The mistake I see most is starting from "when should we list?" Start from your report date instead, and work backward.
As soon as orders are likely: Call me for a pricing conversation, even before orders are official. Ask your lender for your loan payoff and remaining VA entitlement.
90 to 60 days out: Decide: sell, rent or cash offer. Start repairs, touch-ups and decluttering. If renting, interview property managers and call the property appraiser about homestead.
60 to 45 days out: Photos and listing go live. Set your household goods pickup date with the listing in mind.
45 to 30 days out: Review offers, go under contract, get through buyer inspection and appraisal.
Final 2 weeks: Final walkthrough, utilities transfer, sign closing documents in person or remotely.
After you leave: Closing can still happen while you're on the road or at your new duty station.
No time for 90 days? We can still make it work. It just means making decisions faster and possibly pricing a little sharper.
Frequently asked questions
Should I sell or rent my house when I PCS from Eglin AFB?
Sell if you want your VA entitlement back for your next purchase and don't want to manage a rental from a distance. Rent if the home cash-flows after management, insurance and repairs, and you want to own a Crestview rental long term. Run the actual numbers before deciding.
Can I get my VA loan entitlement back if I rent out my house?
Not while the VA loan is still open. Full entitlement can generally be restored after the home is sold and the loan is paid off. You may still have remaining entitlement for another VA loan, so ask your lender to calculate it for your next duty station.
Do I pay capital gains tax if I sell my house after PCSing?
The home sale exclusion normally requires living in the home 2 of the last 5 years. Service members on qualified official extended duty can suspend the 5-year period for up to 10 years. Talk to a tax advisor about your specific dates.
Will I lose my Florida homestead exemption if I rent my house?
Renting a Florida home can affect the homestead exemption, and there are rules specific to service members. Call the Okaloosa County Property Appraiser before you sign a lease.
Can I sell my Crestview house without being there?
Yes. Florida allows remote online notarization, and a local agent can handle showings, vendors, inspections and the appraisal for you.
Is a cash offer a good idea when I have PCS orders?
It can be when speed or major repairs matter more than price. Cash offers usually come in below market value, so get a local agent's pricing first to see what you'd be giving up.
How long does it take to sell a house in Crestview?
It depends on price, condition and the season. Plan on 30 to 45 days from contract to closing for a financed buyer, plus time on market. I'll give you current numbers for your subdivision.
The bottom line
There's no single right answer when PCS orders hit and you own a home in Crestview. There is a right answer for your family, and it comes from real numbers: what the home will sell for today, what it would rent for, what a cash buyer is really offering, and what your next duty station needs from your VA entitlement.
Call or text me at 850-376-0108 with your report date and your address. I'll send you a no-pressure pricing and rent estimate so you can decide with the numbers in front of you, not a postcard.
Consent to be contacted by The Tanya Rivera Group via call, email, and text for real estate services; reply 'stop' to opt out. Message and data rates may apply.
About Tanya Rivera
Tanya Rivera is a REALTOR®, Military Relocation Specialist and leader of the Tanya Rivera Group at The Property Group 850, Inc. A Crestview native and Crestview High graduate, she has helped military families buy and sell across Crestview and the Emerald Coast since 2015.
The Property Group 850, Inc. · 891 S Ferdon Blvd, Crestview, FL 32536 · 850-376-0108 · FL License #3315357
Equal Housing Opportunity. This article is general information only, not legal, tax or financial advice. Confirm your specific situation with your lender, tax advisor, closing agent and the Okaloosa County Property Appraiser.


Comments